
Hi tangent314, my annual premium is $2522.00.Not necessarily. It looks like you get a nice bonus at age 20, and while your increment after that isn't as high as the year 20 bump, it's still quite substantial. We can't work out the IRR after 20 without knowing your annual premium paid though. I'm assuming it's not 0 because otherwise you will be getting 6.7% per year.
You are using an out of date browser. It may not display this or other websites correctly.
You should upgrade or use an alternative browser.
You should upgrade or use an alternative browser.
AIA Prime Life
- Thread starter luvpraline
- Start date
More options
Who Replied?
- Joined
- Jul 26, 2002
- Messages
- 5,136
- Reaction score
- 224
Okay... so at year 20 you would have paid $50440, with a surrender value of $50753. If you continue paying your IRR starts at 1.7% and goes down slowly after that. You should probably evaluate if you really need the life insurance coverage (see the difference between the surrender value and death value).
I noticed that you are reaching 55 soon. Have you considered doing preparation for CPF SA shielding?
I noticed that you are reaching 55 soon. Have you considered doing preparation for CPF SA shielding?
luvpraline
Senior Member
- Joined
- Nov 21, 2005
- Messages
- 867
- Reaction score
- 66
Hi gurus  This is the Post Sales Policy Illustration from AIA's portal: https://docdro.id/a4RQNbl
It looks like the breakeven will only happen at the end of year 20. Appreciate if I could have your advice on these:
1) If the insured decides to surrender the policy at year 20, after what date should he surrender? The policy issue date is: 1-Mar-07. Does it mean he should only surrender the policy after 1-Mar-27?
2) Should he then ignore the annual premium due in Feb 2027 (at year 20), and then surrender the policy after 1-Mar-27?
3) Is year 20 the best time to surrender?
4) Insured has sufficient term coverage until age 65 for death/TPD. He also has hospitalization/DII but no CI insurance other than this AIA Prime Life. To be frank, we're not convinced on the need for CI since most of the costs will be covered by hospitalization insurance right?
5) There is some concern on his part that the term coverage will cease at 65, but by then there will be CPF payout to the beneficiaries upon death, so is it advisable to keep this for the TPD benefit beyond 65?
Any thoughts would be much appreciated. Thanks!
This is the Post Sales Policy Illustration from AIA's portal: https://docdro.id/a4RQNblIt looks like the breakeven will only happen at the end of year 20. Appreciate if I could have your advice on these:
1) If the insured decides to surrender the policy at year 20, after what date should he surrender? The policy issue date is: 1-Mar-07. Does it mean he should only surrender the policy after 1-Mar-27?
2) Should he then ignore the annual premium due in Feb 2027 (at year 20), and then surrender the policy after 1-Mar-27?
3) Is year 20 the best time to surrender?
4) Insured has sufficient term coverage until age 65 for death/TPD. He also has hospitalization/DII but no CI insurance other than this AIA Prime Life. To be frank, we're not convinced on the need for CI since most of the costs will be covered by hospitalization insurance right?
5) There is some concern on his part that the term coverage will cease at 65, but by then there will be CPF payout to the beneficiaries upon death, so is it advisable to keep this for the TPD benefit beyond 65?
Any thoughts would be much appreciated. Thanks!
55@2019, happy to report SA shielded & refunded without a hitch.Okay... so at year 20 you would have paid $50440, with a surrender value of $50753. If you continue paying your IRR starts at 1.7% and goes down slowly after that. You should probably evaluate if you really need the life insurance coverage (see the difference between the surrender value and death value).
I noticed that you are reaching 55 soon. Have you considered doing preparation for CPF SA shielding?
So if I don't need the insurance coverage, it's best to surrender at 20 years in ?
Thanks
- Joined
- Jul 26, 2002
- Messages
- 5,136
- Reaction score
- 224
Hi gurus
It looks like the breakeven will only happen at the end of year 20. Appreciate if I could have your advice on these:
1) If the insured decides to surrender the policy at year 20, after what date should he surrender? The policy issue date is: 1-Mar-07. Does it mean he should only surrender the policy after 1-Mar-27?
2) Should he then ignore the annual premium due in Feb 2027 (at year 20), and then surrender the policy after 1-Mar-27?
3) Is year 20 the best time to surrender?
4) Insured has sufficient term coverage until age 65 for death/TPD. He also has hospitalization/DII but no CI insurance other than this AIA Prime Life. To be frank, we're not convinced on the need for CI since most of the costs will be covered by hospitalization insurance right?
5) There is some concern on his part that the term coverage will cease at 65, but by then there will be CPF payout to the beneficiaries upon death, so is it advisable to keep this for the TPD benefit beyond 65?
Any thoughts would be much appreciated. Thanks!
https://docs.google.com/spreadsheets/d/1OQj0APF_oCc4M2IEDjecAF35TAPPwDtmbdXBscE8I4E/edit?usp=sharing
I've prepared 2 columns. Column D is the IRR from between Year 13 and surrendering at the row's year. Column E is the year to year rate.
You should definitely wait at least until end of Y20. After that I think you should decide on your situation. You should keep the plan if you think you need the coverage provided by the Death Value, or if you think you like the rates given to you ~3.3%-3.7% isn't the most terrible thing, although you can theoretically do better self-investing especially if you can match the PAR fund performance which will net you an extra 1.05-1.45% over this plan.
Depending on the Integrated Shield Plan and riders if any, most of the medical related claims will be covered by that, and the remaining using medishield. Loss of income past the DII waiting period is covered by DII, maybe 2 months of company provided hospitalization leave if that qualifies. Whatever else that needs to be covered, well if there is insufficient savings then you can look into purchasing standalone term CI or continue with your AIA plan.
TPD covers for the loss of 2 out of 6 of your eyes, hands and feet. While it sucks to have that happen, having more excess to cash when it happens maybe nice but doesn't feel essential to me.
55@2019, happy to report SA shielded & refunded without a hitch. So if I don't need the insurance coverage, it's best to surrender at 20 years in ?
Thanks
Yes. Unless you like the year to year rates like I've mentioned above
luvpraline
Senior Member
- Joined
- Nov 21, 2005
- Messages
- 867
- Reaction score
- 66
https://docs.google.com/spreadsheets/d/1OQj0APF_oCc4M2IEDjecAF35TAPPwDtmbdXBscE8I4E/edit?usp=sharing
I've prepared 2 columns. Column D is the IRR from between Year 13 and surrendering at the row's year. Column E is the year to year rate.
You should definitely wait at least until end of Y20. After that I think you should decide on your situation. You should keep the plan if you think you need the coverage provided by the Death Value, or if you think you like the rates given to you ~3.3%-3.7% isn't the most terrible thing, although you can theoretically do better self-investing especially if you can match the PAR fund performance which will net you an extra 1.05-1.45% over this plan.
Depending on the Integrated Shield Plan and riders if any, most of the medical related claims will be covered by that, and the remaining using medishield. Loss of income past the DII waiting period is covered by DII, maybe 2 months of company provided hospitalization leave if that qualifies. Whatever else that needs to be covered, well if there is insufficient savings then you can look into purchasing standalone term CI or continue with your AIA plan.
TPD covers for the loss of 2 out of 6 of your eyes, hands and feet. While it sucks to have that happen, having more excess to cash when it happens maybe nice but doesn't feel essential to me.
Thank you so much, tangent314! You're a great help, truly appreciate your kindness
I do think that 3.3%-3.7% isn't shabby, it is just the uncertainty of the non-guaranteed portion that worries me. But as you've advised, I will re-evaluate the situation after the end of Y20. If got room financially, maybe can continue with this policy.
Do the values in the post-sales policy illustration which I shared change every year?
Also, you mentioned self-investing. Do you have any recommendations on where I should start looking at?
- Joined
- Jul 26, 2002
- Messages
- 5,136
- Reaction score
- 224
I do think that 3.3%-3.7% isn't shabby, it is just the uncertainty of the non-guaranteed portion that worries me. But as you've advised, I will re-evaluate the situation after the end of Y20. If got room financially, maybe can continue with this policy.
Do the values in the post-sales policy illustration which I shared change every year?
Also, you mentioned self-investing. Do you have any recommendations on where I should start looking at?
Yep, the bonus amount varies every year depending on the performance of the PAR fund from the previous year, so the illustrations will change and you should generate a new one online for the updated projections.
Most of the discussion about self-investing takes place on the Shiny Things thread, you might want to go take a look over there.
luvpraline
Senior Member
- Joined
- Nov 21, 2005
- Messages
- 867
- Reaction score
- 66
Yep, the bonus amount varies every year depending on the performance of the PAR fund from the previous year, so the illustrations will change and you should generate a new one online for the updated projections.
Most of the discussion about self-investing takes place on the Shiny Things thread, you might want to go take a look over there.
Ok, thank you tangent314!
1) If the insured decides to surrender the policy at end of year 20, after what date should he surrender? The policy issue date is: 1-Mar-07. Does it mean he should only surrender the policy after 1-Mar-27?
2) Should he then ignore the annual premium due in Feb 2027 (at year 20), and then surrender the policy after 1-Mar-27?
If anyone knows the answers to the above, pls help. Thanks!
Value.Matrix
Senior Member
- Joined
- Sep 13, 2019
- Messages
- 628
- Reaction score
- 58
Ok, thank you tangent314!
If anyone knows the answers to the above, pls help. Thanks!
Policy Anniversary. So the next year premium should not be paid. If your policy start in 1 March, then the premium due on 1 march next year no need to pay if you want to surrender and get the 20th year surrender value (meaning you paid 20 years liao, so the 21st year premium dun pay)
Last edited:
- Joined
- Jul 26, 2002
- Messages
- 5,136
- Reaction score
- 224
Yes, converting to paid up after year 20 is an option. It's best you talk to your agent about it if you intend to surrender or convert to pay out right after year 20. The agent will figure out for you how to get it done without paying the 21st year premium.
luvpraline
Senior Member
- Joined
- Nov 21, 2005
- Messages
- 867
- Reaction score
- 66
Yes, converting to paid up after year 20 is an option. It's best you talk to your agent about it if you intend to surrender or convert to pay out right after year 20. The agent will figure out for you how to get it done without paying the 21st year premium.
Thanks for the advice, tangent314 & Value.Matrix
Actually, I'm not even aware there is an option to convert to pay out
 How is that different from surrendering the policy? I thought that the only option was to surrender the policy or continue paying...
- Joined
- Jul 26, 2002
- Messages
- 5,136
- Reaction score
- 224
You will have to check with your agent if your plan has the option to be converted to paid up. What happens is that you stop paying the premium but continue to get coverage. The death value and surrender value will be lower, of course, but in most cases should still continue to grow.

iceblendedchoc
Arch-Supremacy Member
- Joined
- Nov 22, 2016
- Messages
- 23,224
- Reaction score
- 10,001
Thanks for the advice, tangent314 & Value.Matrix
Actually, I'm not even aware there is an option to convert to pay out
Or sell the policy to those companies that like to buy insurance policy
Please take a look at the policy wordings.Thanks for the advice, tangent314 & Value.Matrix
Actually, I'm not even aware there is an option to convert to pay out
Prime Life should have a reduced Paid Up option. I have explored this option before and I find that it is not worthwhile (The coverage vs the premium that is sunk in it).
Endowment policy might be resellable (traded) but Prime Life is a whole life policy - Not sure if there's going to be any buyer.
IMHO, if coverage is no longer needed, cash it in for its surrender value after the 20th year (from memory, the terminal bonus will hit the max figure from year 20 onwards). Exactly when to surrender after year 20? You have to decide.
Value.Matrix
Senior Member
- Joined
- Sep 13, 2019
- Messages
- 628
- Reaction score
- 58
Please take a look at the policy wordings.
Prime Life should have a reduced Paid Up option. I have explored this option before and I find that it is not worthwhile (The coverage vs the premium that is sunk in it).
Endowment policy might be resellable (traded) but Prime Life is a whole life policy - Not sure if there's going to be any buyer.
IMHO, if coverage is no longer needed, cash it in for its surrender value after the 20th year (from memory, the terminal bonus will hit the max figure from year 20 onwards). Exactly when to surrender after year 20? You have to decide.
Most resellers wouldn't buy because they also aiming for the 20th bonus. I am likely the only 1 who will take in but at a low rate.
So even if you buy it will be before the 20th year?Most resellers wouldn't buy because they also aiming for the 20th bonus. I am likely the only 1 who will take in but at a low rate.
luvpraline
Senior Member
- Joined
- Nov 21, 2005
- Messages
- 867
- Reaction score
- 66
Thank you to all the gurus for your advice! 
Does anyone know how AIA derives their projected yields at surrender? I wonder what is the formula they use to calculate it? And why their yields look higher?
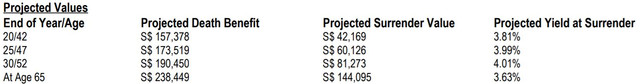
Does anyone know how AIA derives their projected yields at surrender? I wonder what is the formula they use to calculate it? And why their yields look higher?
Value.Matrix
Senior Member
- Joined
- Sep 13, 2019
- Messages
- 628
- Reaction score
- 58
Thank you to all the gurus for your advice!
Does anyone know how AIA derives their projected yields at surrender? I wonder what is the formula they use to calculate it? And why their yields look higher?
Based on IRR (internal rate of return) which factors in the time money is put in. 4% IRR for a lump sum investment vs a 4% IRR cashflow is different. It just means the money you put inside earns a 4% interest.
E.g 100k 4% IRR 10 years is 148k
Vs 100k 4% IRR split into 10 payments in 10 years is 125k
Edit: i buy whole life plans pass 20 years but for investors and under consignment.
everyoneall
Junior Member
- Joined
- Dec 21, 2015
- Messages
- 71
- Reaction score
- 0
AIA Prime Life Policy - Surrender or Keep?
Hi,
I have an AIA Prime Life policy, since Year 1996. I'm wondering if I should surrender it now? Below link is the Post Sales Policy Illustration (31 Dec 2019).
I also have other Term Insurance (Death, TPD, Critical Illness), Hospitalization, Personal Accident plans, etc.
Appreciate you guys for your kind expert advice please.
Thanks.
https://ibb.co/02csLDj
Hi,
I have an AIA Prime Life policy, since Year 1996. I'm wondering if I should surrender it now? Below link is the Post Sales Policy Illustration (31 Dec 2019).
I also have other Term Insurance (Death, TPD, Critical Illness), Hospitalization, Personal Accident plans, etc.
Appreciate you guys for your kind expert advice please.
Thanks.
https://ibb.co/02csLDj
Last edited:
boredboiboi
Master Member
- Joined
- Jun 12, 2010
- Messages
- 4,085
- Reaction score
- 188
Hi,
I have an AIA Prime Life policy, since Year 1996. I'm wondering if I should surrender it now? Below link is the Post Sales Policy Illustration (31 Dec 2019).
I also have other Term Insurance (Death, TPD, Critical Illness), Hospitalization, Personal Accident plans, etc.
Appreciate you guys for your kind expert advice please.
Thanks.
https://ibb.co/02csLDj
What is the premium and coverage for both term and wholelife? Usually wholelife after so long, it will gives u good return already.
Important Forum Advisory Note
This forum is moderated by volunteer moderators who will react only to members' feedback on posts. Moderators are not employees or representatives of HWZ Forums. Forum members and moderators are responsible for their own posts.
Please refer to our Community Guidelines and Standards and Terms and Conditions for more information.
