
Interest is excluded from calculation on topping up RA to new FRS yearly.FRS increases less than 4% per year, interest rate is 4+%
Last edited:
Interest is excluded from calculation on topping up RA to new FRS yearly.FRS increases less than 4% per year, interest rate is 4+%

Good point, for RAs only. I corrected the post.Given that FRS increases every year, I should be able to still do cash top-up to the new FRS mark and get tax relief right unless the interest you get for that year is counted in.

So far, if you had hit SA max, the interest usually will be more than the increase in SA ceilingGood point, for RAs only. I corrected the post.
Of course you should weigh the value of the RA tax relief(s), if any, against the 4+% interest you could be earning with a higher-than-FRS RA balance (and the asset protection benefits with a higher RA balance).
Yes, that’s for SA. The tax relief ruleset for RAs is slightly different.So far, if you had hit SA max, the interest usually will be more than the increase in SA ceiling
Interest is excluded from calculation on topping up RA to new FRS yearly.
I thought RA tax relief only for people who did not reach FRS in SA before RA is created.
once SA/RA reaches FRS, that's it for retirement top up tax relief, correct me if I am wrong.
can top up RA does not equal to tax relief.
Learn to read and interpret IRAS tax rules properly! He posted as a reply!

https://www.cpf.gov.sg/member/faq/g...t-is-the-maximum-amt-of-top-ups-i-can-receiveI thought RA tax relief only for people who did not reach FRS in SA before RA is created.
once SA/RA reaches FRS, that's it for retirement top up tax relief, correct me if I am wrong.
can top up RA does not equal to tax relief.
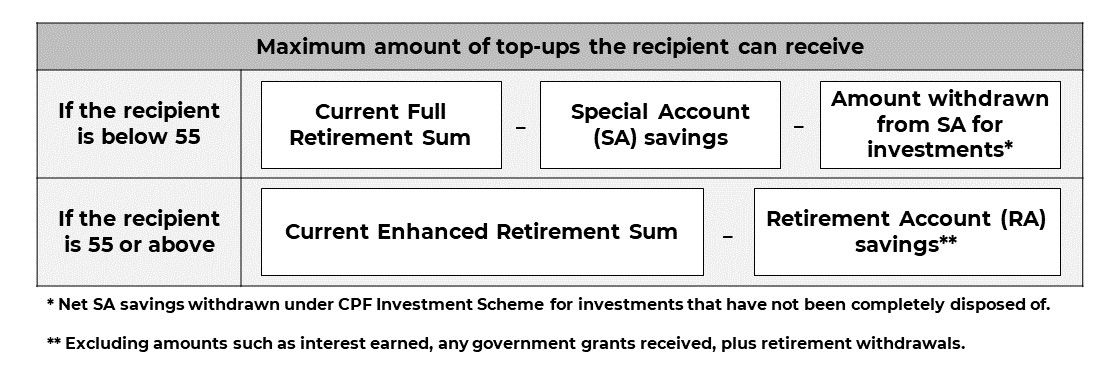
Dun anyhow post link! This has nothing to do with TAX RELIEF!
Since you are such a rude person, I will just reply this one time to you.Dun anyhow post link! This has nothing to do with TAX RELIEF!
The correct IRAS Link already posted before you!
Just because you have a Special Account funded to (or above) the Full Retirement Sum doesn't necessarily mean your Retirement Account will always be funded at or above the Full Retirement Sum. The CPF Investment Scheme (SA) is one way there could be divergence. Another way is that the FRS is applied differently to RAs for tax relief eligibility purposes. When the FRS is raised there may be a new tax relief opportunity with RA. Royalmix posted the link to the details.I thought RA tax relief only for people who did not reach FRS in SA before RA is created.
That's not a correct statement for RA as you've written it. A Retirement Account can reach the FRS but then be eligible in the future for tax relief (when the FRS is raised).once SA/RA reaches FRS, that's it for retirement top up tax relief, correct me if I am wrong.
Yup.. can top up RA does not equal to tax relief.I thought RA tax relief only for people who did not reach FRS in SA before RA is created.
once SA/RA reaches FRS, that's it for retirement top up tax relief, correct me if I am wrong.
can top up RA does not equal to tax relief.

I will believe it when I see evidence that someone with more than FRS when RA creation, but can subsequently top up RA and get tax relief.Yup.. can top up RA does not equal to tax relief.
Believe by default.. your RA will be at FRS at age 55( provide your SA+RA exceed FRS).
So next following year, can top up the difference to the new FRS amount … this amount can have tax relief . Any more extra top up to the RA will not give your tax relief.
Anyway, can see the require top up to get the tax relief in your CPF account.
But then, who knows what changes will be made when you reach 55
Tax relief not only for working income. It can help draw down more from SRS, too. Don’t underestimate its utilityhopefully i will be retired by 55 and do not need any tax relief if income is less than 20k!
By default the CPF Board will only fund your Retirement Account on your 55th birthday to the then current Full Retirement Sum. Your Special Account could have $1 million in it, but that doesn't matter for these purposes. The CPF Board stops its automatic 55th birthday sweep once your RA reaches the FRS in effect on your 55th birthday, or SA and OA dollars are exhausted, whichever comes first.I will believe it when I see evidence that someone with more than FRS when RA creation, but can subsequently top up RA and get tax relief.
How is IRAS's text ambiguous? Which part is unclear to you?So far I only see guess based on ambiguous text from IRAS page.
Yes, you would qualify for tax relief in the scenario you describe, assuming you're otherwise eligible (haven't reached the $8,000 limit, haven't reached the $80,000 total tax relief limit, still have taxable income, etc.)So to sum it up, if I have more than FRS in my SA before 55, my RA will be created with the FRS amount transferred from my SA. Even if RA increases through interest earned, I can still top up RA the difference btw the previous year's FRS and the new FRS and get tax relief?
Yup.. you are correct.So to sum it up, if I have more than FRS in my SA before 55, my RA will be created with the FRS amount transferred from my SA. Even if RA increases through interest earned, I can still top up RA the difference btw the previous year's FRS and the new FRS and get tax relief? Or did i get it wrong again.

Yes, you would qualify for tax relief in the scenario you describe, assuming you're otherwise eligible (haven't reached the $8,000 limit, haven't reached the $80,000 total tax relief limit, still have taxable income, etc.)
thanks. Let's see how things have changed (rules wise and personal circumstances) when I hit 55. No point thinking about it now (nor can I do anything to prepare for it) anywayYup.. you are correct.
you can check it out yourself in your cpf account on the allowable cash top up for tax relief when you reached 55 provided no changes of rule then
