
Daisin is in deep **** recently isnt it? They managed to delay their short-term debt repayment by another 3 mths? Too risky to look at this co.Just give a few example, didn't study much, just base on data provide by Vince.
Dasin Retail Trust
Gearing ratio 36.7%
Fix Rate 24.1% (interest rate will be higher when taking new loan)(same as our property loan fix rate better in the high inflation period)
ARA US Hopsitality
Gearing ratio 48.4% (max 50%)
Fix Rate 76.6%
Suntec
Gearing ratio 44.3%
Fix Rate 57%
(debts mostly mature after 5 years so not so bad)
Elite Commercial
Gearing ratio 42.1%
Fix Rate 63%
IREIT Global
Gearing ratio 35.8%
Fix Rate 25.3%
Mapletree has the best debts management.
You are using an out of date browser. It may not display this or other websites correctly.
You should upgrade or use an alternative browser.
You should upgrade or use an alternative browser.
General S-REITs Discussion Thread
- Thread starter Dividends Warrior
- Start date
More options
Who Replied?Yes, that's why always check their debts, debts maturity, gearing ratio, revenue, net income etc.....Daisin is in deep **** recently isnt it? They managed to delay their short-term debt repayment by another 3 mths? Too risky to look at this co.
Not just price movement, unless you are trading.
All these in their quarterly/ semi annually report.
You may find your ans here w some gearing ratios and proposed reits favoured
https://www.theedgesingapore.com/capital/brokers-calls/bumpy-ride-ahead-s-reits-rhb
https://www.theedgesingapore.com/capital/brokers-calls/bumpy-ride-ahead-s-reits-rhb
Anyone expecting Reits prices to go lower when interest rates rises?
Some of the REITs already price in (those drop alot recently).
Some REITs with bad debts management likely to be affected, when the interest rate really go up.
I think partially priced in. When actual comes, panic again.
"Nevertheless, Natarajan thinks that S-REITs are better prepared to ride an interest rate upcycle, saying from a balance sheet standpoint, S-REITs are well poised to weather the rate hikes, with sector gearing at 37%, well below the regulatory limit of 50%.You may find your ans here w some gearing ratios and proposed reits favoured
https://www.theedgesingapore.com/capital/brokers-calls/bumpy-ride-ahead-s-reits-rhb
In addition, nearly 77% of S-REITs debts are hedged, with sector average interest cover of 5.2x and weighted average debt maturity of 2.8 years."
The writer only touching the surface. This answer will lead to misjudgment.
You buy SREITs for long term investment, better don't monitor the price too much. It's more for passive income.I think partially priced in. When actual comes, panic again.
The more you monitor, the more emotion you will be.
SP500 drop below 200SMA, maybe another crash coming, should you panic?
Inflation coming or it's already here, should you panic?
The easiest way to reduce the impact of interest rates will be to convert debt to equity by (i) private placement at discounted prices that are 'unfair' to retail investors, (ii) rights issue/preferential offering. Those who have been investing in REITs long enough know that some REIT managers like to do (i), some like to do (ii). 
The last time a large number of REITs issued new shares was probably the GFC. But that time, the price of the rights share was below the NAV, so effectively, its like an automatic discount, who wouldn't want to buy. But if the price of rights share is above NAV (even if slightly cheaper than market price), I will have to do more due diligence...
The last time a large number of REITs issued new shares was probably the GFC. But that time, the price of the rights share was below the NAV, so effectively, its like an automatic discount, who wouldn't want to buy. But if the price of rights share is above NAV (even if slightly cheaper than market price), I will have to do more due diligence...
If only there is any property acquire then the REITs will do PP/OP/Right Issue. If just for servicing the debts, then actually it's a red flag for this kind of REITs.The easiest way to reduce the impact of interest rates will be to convert debt to equity by (i) private placement at discounted prices that are 'unfair' to retail investors, (ii) rights issue/preferential offering. Those who have been investing in REITs long enough know that some REIT managers like to do (i), some like to do (ii).
The last time a large number of REITs issued new shares was probably the GFC. But that time, the price of the rights share was below the NAV, so effectively, its like an automatic discount, who wouldn't want to buy. But if the price of rights share is above NAV (even if slightly cheaper than market price), I will have to do more due diligence...

If only there is any property acquire then the REITs will do PP/OP/Right Issue. If just for servicing the debts, then actually it's a red flag for this kind of REITs.
Its pretty common and its not necessarily wrong to pay back expensive debt with 'cheap equity', take for example this recent private placement by a 'branded' REIT in 2021. 42.5% for debt repayment, 57.5% to buy property. But of course in some cases its a red flag - but if the REIT is doing it out of desperation, there will be many red flags earlier already (not a REIT, but Sembmarine should be familiar to everyone....
 )

USE OF PROCEEDSIts pretty common and its not necessarily wrong to pay back expensive debt with 'cheap equity', take for example this recent private placement by a 'branded' REIT in 2021. 42.5% for debt repayment, 57.5% to buy property. But of course in some cases its a red flag - but if the REIT is doing it out of desperation, there will be many red flags earlier already (not a REIT, but Sembmarine should be familiar to everyone....
Further to the Launch Announcement and subject to relevant laws and regulations, the
Manager intends to use the gross proceeds of approximately S$150.0 million from the
Private Placement in the following manner:
(i) approximately S$146.2 million (which is equivalent to 97.5% of the gross proceeds
of the Private Placement) to finance part of the total acquisition cost of the proposed
Acquisition and the associated costs;
(ii) approximately S$3.8 million (which is equivalent to 2.5% of the gross proceeds of
the Private Placement) to pay the estimated fees and expenses, including,
professional fees and expenses, incurred or to be incurred by CLCT in connection
with the Private Placement,
with the balance of the gross proceeds of the Private Placement, if any, to be used for
general corporate and/or working capital purposes.
Depend on the management, so need to check the detail if there is a right issue and the FA.
I brought Sembmarine too for short term trade, end up stuck

Dividends Warrior
High Supremacy Member
- Joined
- Nov 7, 2010
- Messages
- 25,029
- Reaction score
- 3,044
CD Season is here again!
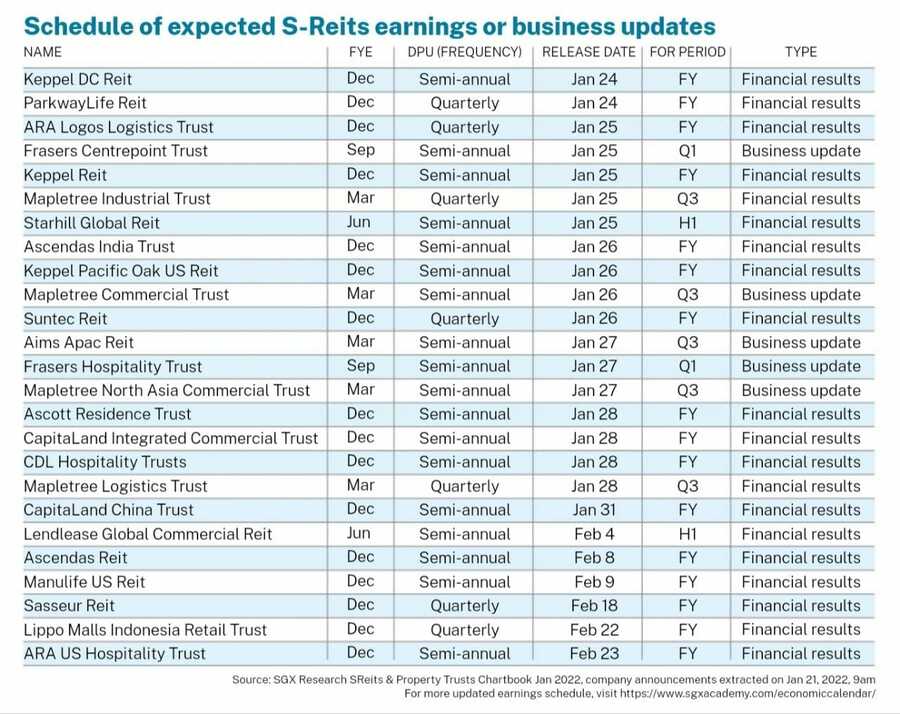
Dividend coming, huat ah!CD Season is here again!


Lasogette
Supremacy Member
- Joined
- Dec 20, 2012
- Messages
- 8,166
- Reaction score
- 4,527
Nice. Sir u retired liao ?CD Season is here again!

Shion
Senior Mentor
- Joined
- Oct 24, 2008
- Messages
- 377,087
- Reaction score
- 122,919
Rising risk-free rates may continue to exert upward pressure on REIT yields
https://www.theedgesingapore.com/ca...ay-continue-exert-upward-pressure-reit-yields


Dividends Warrior
High Supremacy Member
- Joined
- Nov 7, 2010
- Messages
- 25,029
- Reaction score
- 3,044
Not yet.Nice. Sir u retired liao ?

Need to hit $40k annual dividends.

Important Forum Advisory Note
This forum is moderated by volunteer moderators who will react only to members' feedback on posts. Moderators are not employees or representatives of HWZ Forums. Forum members and moderators are responsible for their own posts.
Please refer to our Community Guidelines and Standards and Terms and Conditions for more information.
