General S-REITs Discussion Thread

Dividends Warrior

High Supremacy Member
Joined
Nov 7, 2010
Messages
25,029
Reaction score
3,047
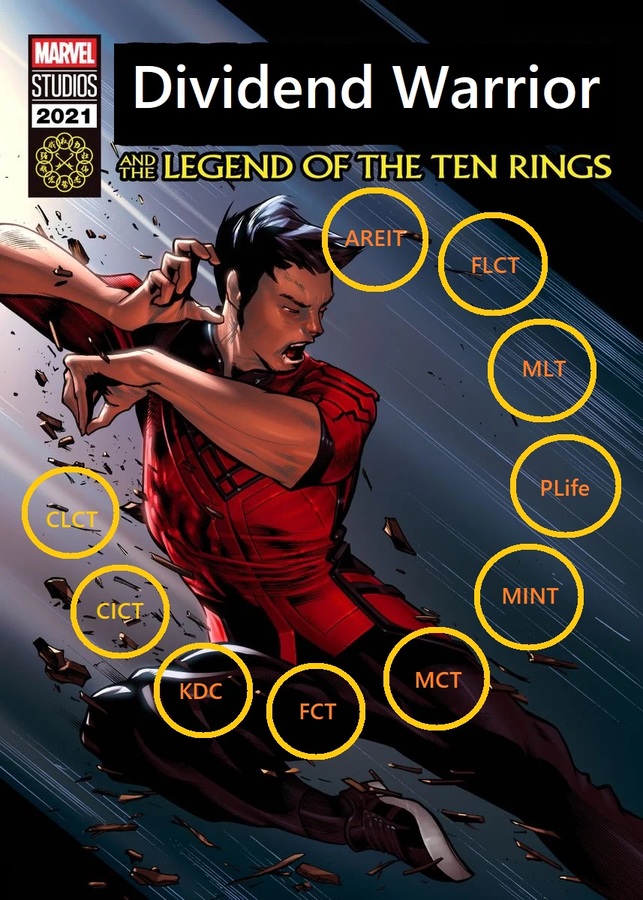
Ten Rings flying! :oops:

843e5736074c54248e6906772123ab7917fc3680.jpg
 

dappermen

Banned
Joined
Mar 5, 2017
Messages
8,663
Reaction score
1,017
Last edited:

Andrew833

Arch-Supremacy Member
Joined
Apr 7, 2017
Messages
17,567
Reaction score
6,144
Means got chance to load more before it chiong?
FLCT recently more red than green,
Current chart look likely it will test $1.38. If break support will goes below $1.38. Next support is $1.33.
After make a bottom, will rebound, how far it will chiong still a question mark.
 

yumsang

Arch-Supremacy Member
Joined
Apr 24, 2020
Messages
10,222
Reaction score
1,941
FLCT recently more red than green,
Current chart look likely it will test $1.38. If break support will goes below $1.38. Next support is $1.33.
After make a bottom, will rebound, how far it will chiong still a question mark.
hope it can drop to those prices.
 

keithster

Arch-Supremacy Member
Joined
Mar 16, 2004
Messages
11,165
Reaction score
154
i only have 5 rings... lacking on commercial mostly.

looking at CICT next. any comment if it is a good reit to buy?

will not consider KDC... is deteriorating
 

dappermen

Banned
Joined
Mar 5, 2017
Messages
8,663
Reaction score
1,017
will this alleviate some fears of Constant hike in interest rates?

REITs can offset impact of rising rates with a more defensive portfolio?​

https://www.theedgesingapore.com/ca...-impact-rising-rates-more-defensive-portfolio


... For some reason, investors just do not value US S-REITs ?!?!!?!? with commercial properties at more compressed yields. This is despite a rally of sorts in Singapore-based office S-REITs ?— even in the face of higher interest rates.
The US office REITs, which include Keppel Pacific Oak US REIT (KORE), Manulife US REIT (MUST) and Prime US REIT, are trading at DPU yields of between 8% and 9% and discounts to net asset value (NAV). United Hampshire US REIT, which owns retail properties, is trading at 10%.....


Keppac is fantastic! the only US Reits that is worth your attn too! not other Keppels which has power of Shangchi- Rings!!!!!!!!!!!!!! & if the 10rings are trustable , UOB KH a respectable Broker deserved some readings too
& are institutional brains diff from retail, really? i disagree
i didnt imitate UOBKH anyway, i dont believe in imitating, i trusted many purposely observed what Cathie Wood does & then short against!

I own Sassy Sasseur all along as well as latest Keppac , which of the 5 u own, dont Evn hve to imitate but at least shd have 2 or so???


UOBKH TOP YIELD STOCK PICKS :
UtdHampshReitUSD BUY 0.95 0.625 52.0 1.6 14.5 11.2 10.0
ManulifeReit USD BUY 0.80 0.65 23.1 0.8 15.3 12.4 9.3
Sasseur REIT BUY 1.12 0.845 32.5 6.3 17.0 10.2 9.0
KepPacOakReitUSD BUY 1.10 0.71 54.9 (4.1) 15.1 11.3 8.9

Ascendas Reit BUY 3.92 2.77 41.5 0.4 20.2 17.9 6.0
(read only p2& 6 since this is a thread purely on Reits
https://mcusercontent.com/ccf83de3f...il&utm_term=0_d59b491060-47e5dc392f-225545766)
 
Last edited:

Shion

Senior Mentor
Joined
Oct 24, 2008
Messages
377,207
Reaction score
123,027

Pure-play China S-Reits record strong 2021 growth​


https://www.businesstimes.com.sg/companies-markets/pure-play-china-s-reits-record-strong-2021-growth
LISTED on SGX are 4 S-Reits and 1 property trust with pure exposure to China. These trusts have assets across sub-sectors such as retail malls, logistics and industrial, and office and business parks based in China.

All 5 trusts have recorded stronger rental income and declared increases in distributions made to unitholders for full year 2021. Common themes across their full-year earnings were resilient portfolio occupancy rates, recovery in shopper footfalls and tenant sales, and contributions from acquisitions despite recent Covid-19 resurgences.

CapitaLand China Trust (CLCT), which is diversified across 11 retail assets, 5 business parks and 4 logistics properties, reported 37.5 per cent higher FY2021 distribution per unit (DPU) and 85.2 per cent higher annual net property income (NPI) for the year. Increases were due to new contributions from its recently acquired logistics and business park portfolios, Rock Square and CapitaMall Nuohemule.

CLCT noted better occupancy rate of 96.3 per cent in FY2021, alongside higher tenant sales and shopper traffic of 16.1 per cent and 9.3 per cent respectively despite mall closures and restrictions due to sporadic Covid-19 outbreaks.

Beyond retail malls, CLCT now has a combined 21.9 per cent exposure to new economy assets through its business park and logistics portfolio which registered 7.0 per cent and 2.7 per cent in rental reversion respectively in FY2021. CLCT is also the first S-Reit to secure a loan linked to the sustainability performance of a China portfolio.

ZllqOos.jpg


Sasseur Reit and its portfolio of 4 retail outlet malls posted 8.5 per cent growth in DPU and 10.1 per cent growth in entrusted management agreement (EMA) rental income in FY2021, despite Covid-19 disruptions.

The Reit saw continued robust consumption trends in the cities where its outlets are located, coupled with intensive promotional efforts with tenants which drove higher sales. Its portfolio occupancy rate rose to 94.5 per cent in Q42021 compared to 93.7 per cent in Q32021. The Reit believes that it will continue to benefit from China's domestic consumption.

EC World Reit (ECW) is a specialised logistics and e-commerce logistics Reit with 8 properties in Hangzhou and Wuhan. The Reit recorded 12.7 per cent growth in NPI and 16.9 per cent increase in DPU, largely due to the absence of one-off rebates provided to tenants in FY2020. Its portfolio has an occupancy rate of 99.2 per cent as at Dec 31, 2021 and is diversified across 3 segments: e-commerce logistics (41.8 per cent of portfolio valuation), port logistics (40.5 per cent), and specialised logistics (17.8 per cent).

On Jan 10, 2022, ECW received a formal notice in relation to the compulsory expropriation of Fu Zhuo Industrial and is entitled to receive compensation based on the expropriation valuation. The Reit does not expect the compulsory expropriation to have a material impact on its portfolio and Fu Zhuo Industrial accounts for under 1.5 per cent of its portfolio valuation and 1.6 per cent of its NPI in FY2021.

BHG Retail Reit across its 6 retail malls reported increases of 14.9 per cent in NPI and 11.3 per cent in DPU for FY2021. The Reit noted that its malls continued to see healthy leasing demands with occupancy rate at 97.0 per cent as at Dec 31, 2021 alongside healthy retention rates. The Reit will remain cautious about risks of Covid-19 resurgence and continues to refresh its malls' offerings to pursue growth opportunities.

Dasin Retail Trust has a portfolio of 7 retail malls and registered increases of 10.9 per cent in NPI and 32.5 per cent in DPU for FY2021. It maintains an occupancy rate of 93.9 per cent across a diversified tenant base with no single trade sector contributing over 25.0 per cent of its gross rental income. The trust manager also looks to source new expansion opportunities with its new strategic partner and major shareholder Sino-Ocean Capital. SGX RESEARCH

 

vsvs24

Arch-Supremacy Member
Joined
Feb 3, 2018
Messages
11,383
Reaction score
3,733

Pure-play China S-Reits record strong 2021 growth​


https://www.businesstimes.com.sg/companies-markets/pure-play-china-s-reits-record-strong-2021-growth
LISTED on SGX are 4 S-Reits and 1 property trust with pure exposure to China. These trusts have assets across sub-sectors such as retail malls, logistics and industrial, and office and business parks based in China.

All 5 trusts have recorded stronger rental income and declared increases in distributions made to unitholders for full year 2021. Common themes across their full-year earnings were resilient portfolio occupancy rates, recovery in shopper footfalls and tenant sales, and contributions from acquisitions despite recent Covid-19 resurgences.

CapitaLand China Trust (CLCT), which is diversified across 11 retail assets, 5 business parks and 4 logistics properties, reported 37.5 per cent higher FY2021 distribution per unit (DPU) and 85.2 per cent higher annual net property income (NPI) for the year. Increases were due to new contributions from its recently acquired logistics and business park portfolios, Rock Square and CapitaMall Nuohemule.

CLCT noted better occupancy rate of 96.3 per cent in FY2021, alongside higher tenant sales and shopper traffic of 16.1 per cent and 9.3 per cent respectively despite mall closures and restrictions due to sporadic Covid-19 outbreaks.

Beyond retail malls, CLCT now has a combined 21.9 per cent exposure to new economy assets through its business park and logistics portfolio which registered 7.0 per cent and 2.7 per cent in rental reversion respectively in FY2021. CLCT is also the first S-Reit to secure a loan linked to the sustainability performance of a China portfolio.

ZllqOos.jpg


Sasseur Reit and its portfolio of 4 retail outlet malls posted 8.5 per cent growth in DPU and 10.1 per cent growth in entrusted management agreement (EMA) rental income in FY2021, despite Covid-19 disruptions.

The Reit saw continued robust consumption trends in the cities where its outlets are located, coupled with intensive promotional efforts with tenants which drove higher sales. Its portfolio occupancy rate rose to 94.5 per cent in Q42021 compared to 93.7 per cent in Q32021. The Reit believes that it will continue to benefit from China's domestic consumption.

EC World Reit (ECW) is a specialised logistics and e-commerce logistics Reit with 8 properties in Hangzhou and Wuhan. The Reit recorded 12.7 per cent growth in NPI and 16.9 per cent increase in DPU, largely due to the absence of one-off rebates provided to tenants in FY2020. Its portfolio has an occupancy rate of 99.2 per cent as at Dec 31, 2021 and is diversified across 3 segments: e-commerce logistics (41.8 per cent of portfolio valuation), port logistics (40.5 per cent), and specialised logistics (17.8 per cent).

On Jan 10, 2022, ECW received a formal notice in relation to the compulsory expropriation of Fu Zhuo Industrial and is entitled to receive compensation based on the expropriation valuation. The Reit does not expect the compulsory expropriation to have a material impact on its portfolio and Fu Zhuo Industrial accounts for under 1.5 per cent of its portfolio valuation and 1.6 per cent of its NPI in FY2021.

BHG Retail Reit across its 6 retail malls reported increases of 14.9 per cent in NPI and 11.3 per cent in DPU for FY2021. The Reit noted that its malls continued to see healthy leasing demands with occupancy rate at 97.0 per cent as at Dec 31, 2021 alongside healthy retention rates. The Reit will remain cautious about risks of Covid-19 resurgence and continues to refresh its malls' offerings to pursue growth opportunities.

Dasin Retail Trust has a portfolio of 7 retail malls and registered increases of 10.9 per cent in NPI and 32.5 per cent in DPU for FY2021. It maintains an occupancy rate of 93.9 per cent across a diversified tenant base with no single trade sector contributing over 25.0 per cent of its gross rental income. The trust manager also looks to source new expansion opportunities with its new strategic partner and major shareholder Sino-Ocean Capital. SGX RESEARCH
Hmm. Dasin can survive or not ?

The COVID situation in China is also worrying. Can lockdown an important city like Shenzhen for a week.
 
Important Forum Advisory Note
This forum is moderated by volunteer moderators who will react only to members' feedback on posts. Moderators are not employees or representatives of HWZ Forums. Forum members and moderators are responsible for their own posts. Please refer to our Community Guidelines and Standards and Terms and Conditions for more information.
Top