General S-REITs Discussion Thread

dappermen

Banned
Joined
Mar 5, 2017
Messages
8,663
Reaction score
1,017
What is HST? Tried Google it but not found......
not a reit hence u cannot locate its counter

Not a thread to delve into non-reits

anyway alot of discussion on CICT

https://www.theedgesingapore.com/ca...n-three-months-capitaland-investment-benefitsand such trusts, not Reits though
https://www.theedgesingapore.com/capital/reits/kits-manager-proposes-raise-base-fee-10-times
everything related to properties
https://www.theedgesingapore.com/ne...-lots-tanglin-shopping-centre-collective-sale

for those into this reits: Listed on Sgx too

United Hampshire US REIT​


https://register.gotowebinar.com/register/7867005018521378572?source=eDM
 
Last edited:

dappermen

Banned
Joined
Mar 5, 2017
Messages
8,663
Reaction score
1,017
Not all r experts like some of u ..........

Made-simple for u:


2) Sponsor = alwys nag by some (i dont think this is a Major issue at all)
3) Yield (is it artificially increasing just to attract)
4) Tenants? (committed occupancy)

using ratios n financial :
P/B ratio > 1 (Investors r valuing the Reits more than all its net assets) - but too simplistic
can still trade abv its bk value
it can be due to qlty of Mgr or strong sponsors!

Fi strength, Gearing Ratio (leverage) - usu 50%
Cost of Financing (more spent on servicing debt?!)
Interest coverage! (more income to service loan)
Fixed Rate?

Weighted average interest rate is lower or higher
Portfolio Unencumbered up to ?
as Unencumbered asset is much easier to sell!

Leasing volume up
WALE up ?
Tls and free rent down?
Base rent up?
Net effective rent up?


Revenue - a must too to look@
did he mention Net Property Income (up by)?


and also ref to:
https://forums.hardwarezone.com.sg/...ussion-thread.4313167/page-163#post-140192679https://forums.hardwarezone.com.sg/...ussion-thread.4313167/page-163#post-140184496

but how does Reits Grow
Acq
Rental Increase (i think esp in sg, though u shdnt scare of your tenants by keep increase)
Asset Enhancemt....Capex to renovate... improve Gross Floor Area (i think Tiong bharu Plaza did well for that)


if just to base on financial info: i ran this in 2021 (need to re run it again for 2022)
i ran before a mixture of ...........these r the shortlisted
(the top 10++ r listed from the bottom , those shaded lightly - is Forgettabble & anything that cannot give a decent yield of mOre than 5%++ forget it man pls)

Trading NameTrading CodeMkt Cap ($M)Tot. Rev ($M)P/EYield (%)SectorNet Profit %ROE %Price/CFDebt/Eqty1-yr %Rev. Chg.P/B
Mapletree Log TrM44U
9178.636​
592.5​
19.61​
3.71​
Real Estate
79.64​
8.18​
71.92​
17.71​
1.47​
CapLand IntCom TC38U
14052.911​
1072.479​
14.64​
4.18​
Real Estate
78.73​
8.14​
16.57​
49.16​
0.97​
Frasers L&C TrBUOU
5617.791​
444.985​
8.15​
4.69​
Real Estate
113.91​
16.83​
11.08​
66.76​
0.97​
Global InvB73
263.748​
18.766​
17.33​
5.23​
Collective Investments
76.3​
4.53​
0​
0.75​
Starburst40D
48.784​
21.772​
5.4​
5.32​
Industrial & Commercial Services
41.95​
33.6​
4.78​
67.26​
3.97​
Low Keng HuatF1E
347.244​
73.351​
7.13​
5.32​
Industrial & Commercial Services
65.26​
7.21​
6.5​
119.92​
0.48​
ARA LOGOS Log TrK2LU
1276.153​
126.199​
5.99​
5.51​
Real Estate
158.69​
21.47​
6.36​
81.1​
11.97​
0.84​
ESR-REITJ91U
1780.582​
236.01​
17.64​
5.93​
Real Estate
43.33​
5.55​
88.39​
-0.93​
0.87​
Ascendas-iTrustCY6U
1682.271​
188.054​
12.88​
5.95​
Real Estate
75.05​
10.26​
11.87​
62.37​
-6​
1.21​
IREIT Global SGDUD1U
743.303​
60.238​
14.49​
6.87​
Real Estate
52.14​
4.95​
65.33​
0.97​
Cromwell Reit EURCWBU
1409.613​
186.972​
16.23​
6.91​
Real Estate
42.45​
6.07​
62.67​
1.05​
Sabana ReitM1GU
468.622​
76.53​
11.69​
7.03​
Real Estate
52.39​
7.36​
67.21​
3.6​
0.68​
Sasseur ReitCRPU
1157.569​
131.722​
21.5​
7.37​
Real Estate
40.57​
4.79​
?
44.08​
14.62​
0.64​
EliteComREIT GBPMXNU
313.457​
27.543​
14.68​
7.7​
Real Estate
51.08​
5.67​
50.06​
1.15​
KepPacOakReitUSDCMOU
787.392​
137.473​
9.78​
8.28​
Real Estate
53.33​
9.58​
66.02​
2.09​
0.87​
Hotung InvBLS
184.203​
49.275​
6.66​
10.9​
Banking & Investment Services
56.23​
8.47​
6.56​
0​
0.65​
 
Last edited:

Shion

Senior Mentor
Joined
Oct 24, 2008
Messages
377,308
Reaction score
123,107

Singapore office S-Reits poised to benefit from positive rental momentum​


https://www.businesstimes.com.sg/co...ised-to-benefit-from-positive-rental-momentum
SINGAPORE'S Central Business District (CBD) saw Grade A office rents record the fastest quarterly growth since rents turned around in Q2 2021, according to JLL Singapore in a recent report.

Grade A office rents in the CBD rose 2.3 per cent to S$10.46 per square foot (psf) per month (pm) in the latest quarter, up from Q4 2021's S$10.23. Rental rates have recovered by 6.9 per cent from its recent lows in Q1 2021.

Office Reits may also be poised to benefit from a growth in demand for office space as up to 75 per cent of office workers are allowed to return to their workplaces, even as hybrid working continues.

guVTVN1.jpg


Listed on SGX are 5 S-Reits with Singapore office properties in their portfolios. They are, Keppel Reit which is a pure-play office S-Reit, and diversified S-Reits CapitaLand Integrated Commercial Trust (CICT), Suntec Reit, Mapletree Commercial Trust (MCT) and OUE Commercial Reit (OUE C-Reit). Keppel Reit in FY21 had a tenant retention rate of 62 per cent and noted that a majority of new and expansion leases were in Singapore.

Its weighted average signing rent for Singapore office leases was approximately S$10.56 psf pm.

Building valuations for Marina Bay Financial Centre Towers 1 & 2, One Raffles Quay and Keppel Bay Tower increased due to higher rental rates.

OUE C-Reit which has a portfolio of 3 office properties in Singapore's CBD noted in its FY21 results that average passing rents of Singapore office properties at Dec 2021 were higher year on year, with OUE Bayfront hitting a high of S$12.49 psf due to the successful renewal of an anchor tenant. The Reit expects positive leasing momentum to continue in 2022, supported by the technology sector amid a limited supply pipeline.

CICT recently announced its proposed acquisition of 70 per cent interest in 79 Robinson Road which has a building occupancy rate of 92.9 per cent. The acquisition is expected to offer pro forma annualised net property income yield of 4 per cent, distribution per unit accretion of 2.9 per cent, and is expected to complete in Q2 2022.

Across the broader S-Reits sector, S-Reits demonstrated resiliency amid the backdrop of rising inflation and a rate hike cycle with the iEdge S-Reit Index posting 1.3 per cent total returns in Q1 2022, outperforming the average decline of 4.9 per cent across global Reit hubs.

Despite rising interest rates, S-Reits have an average distribution yield of 6.3 per cent, around 400 bps spread over Singapore's 10-year government bond yields. The sector has an average gearing ratio of about 37 per cent (current regulatory ceiling is 50 per cent) and has an average 75 per cent of their borrowings pegged at fixed rates (entered directly in fixed rates or hedged through floating-to-fixed interest rate swaps).

The top 5 performing S-Reits and property trusts in Q1 2022 averaged 14.1 per cent total returns, outperforming STI's 9.6 per cent, and are mainly from the hospitality and office sub-segments. They are: Suntec Reit (+17.6 per cent), Frasers Hospitality Trust (+15.1 per cent), Far East Hospitality Trust (+13.1 per cent), CDL Hospitality Trusts (+13.0 per cent), and Ascott Residence Trust (+11.5 per cent).

Drivers that potentially drove the sub-segments were the continued reopening theme and relaxation of Covid measures across Singapore and the region, as well as the positive momentum in office rental rates. SGX RESEARCH
 

dappermen

Banned
Joined
Mar 5, 2017
Messages
8,663
Reaction score
1,017
Reits: from pg 12:
https://research.uobkayhian.com/content_download.jsp?id=67278&h=3c8ad764022826cb1e0a2c3ee6d85ef4
REITs - Implications of inverted yield curve on S-REITs.

Risk of the global economy slipping into a recession has increased with an inversion of the US yield curve since 1 Apr 22. SREITs underperformed after the inversion in Nov 06 but performed in line with the broader market after the inversion in Aug 19. The Russia-Ukraine war creates heightened uncertainties and has pushed bond yields higher. BUY ART (Target: S$1.29), FCT (Target: S$2.98), MCT (Target: S$2.48) and MINT (Target: S$3.72). Maintain OVERWEIGHt!!!!!!!
 
Last edited:

dappermen

Banned
Joined
Mar 5, 2017
Messages
8,663
Reaction score
1,017
Not too bad though i didnt really monitor it

if u r into usd reits, the best i can think of is: keppac oak and nothing else

anyway not many here will like to own us-related reits
 

TehSi99

Master Member
Joined
Oct 5, 2018
Messages
4,892
Reaction score
1,318
Not too bad though i didnt really monitor it

if u r into usd reits, the best i can think of is: keppac oak and nothing else

anyway not many here will like to own us-related reits

In fact, I have KepOak. This is the 1st US related reits I have.
 

dappermen

Banned
Joined
Mar 5, 2017
Messages
8,663
Reaction score
1,017
U alwys have Higher taste!!!!!!!!! From sasseur.............!!!!!!!!!!!!!!!!!!!!!!!!!!!!!! wow!!!!!!!!!!!!!!!! NOT many here able to.......although many here have super powers


Dont ever share w anyone, ssssssssssssshhhhhhhhhhhhhhhhhhh ie my first too, love it !
the ONLY diffce is i can only afford very little and regretted not daring ENOUGH
I have KepOak.
 

Andrew833

Arch-Supremacy Member
Joined
Apr 7, 2017
Messages
17,571
Reaction score
6,145
Prime. I think it is a mistake. Looking to sell off. The consolation is the dividend not too bad. But if price drops further, then gg investment.
FY2021 vs FY2020 (USD)
Gross Revenue up 9.2%
Net Property Income up 6%
DPU (in cents) down 2.3%

2H 2021 vs 2H 2020 (USD)
Gross Revenue up 17%
Net Property Income up 14.3%
DPU (in cents) up 0.9%
Dividend 3.36 cents (USD) (0.09 cents paid in 1H2021)
Distribution Reinvestment Plan (DRP) for dividend, see attach

Gearing Ratio up 4.4% to 37.9% yoy
Fixed Rate: 17%
Floating Rate (fixed to swap) 70%, (unswapped) 13%
Floating Rate fixed to swap is similar to hedged, so 17% + 70% = 87% (with risk of higher interest, still manageable)

Debts not well manage in my opinion, FY2022 and FY2023 are 34% of overall debts. That’s one third of the portfolio. The adjusted debts maturity base on assumption, I’m not interested, show me FY2022 report.

Positive consistent rental reversion from 3Q2020 to 4Q2021, average 11.5%
Occupancy 90.3%
Gross revenue and NPI increase due to the acquisition of One Town Center and Sorrento Towers.

Interest rates are expected to rise, based on median forecasts from 12-19 Jan 2022 Reuters poll that showed the Fed raising its key interest rate three times this year, starting March, 0.75%-1.00% by end of 2022, a significant upgrade from two hikes predicted in the Dec survey.

Overall, ok result for FY2021 and 2H2021 is good. Gearing ratio is fine but debts maturity is high. If not for One Town Center and Sorrento Towers, the earning result will be not good.

Price drop usually is a temporary thing, price will consolidate and slowly recover, may even breakout to higher price. If the REITs is doing fine, why sell just because the price drop. Do you notice all REITs or stocks, price goes up and down and up and down. If the REIT or stock FA is still good or ok, then nothing to worry. Look at MINT, SGX chart. If you invest in long term, don't worry too much on price movement. My SGX brought at 10.01, price drop to 8.9x, I'm still holding, today already testing 10.13.
 

Shion

Senior Mentor
Joined
Oct 24, 2008
Messages
377,308
Reaction score
123,107

DBS sees ‘breakout month’ for S-REITs, but warns that focus may soon shift to results and rates​


https://www.theedgesingapore.com/ca...-warns-focus-may-soon-shift-results-and-rates
Singapore REITs (S-REITs) experienced a “breakout month” on news of domestic relaxation and border reopening trends in Singapore, with the FTSE ST Real Estate Investment Trusts Index (FSTREI) climbing 5.5% m-o-m, beating the STI’s rise of 5.1% m-o-m.

In a flash note on April 1, DBS Group Research’s Geraldine Wong and Derek Tan says catalysts for the sector were “a mixed bag”. But there was a lift-off from January and February, when many stocks reached a 52-week low.

They add that while sentiment continues to be mixed given the risk of geopolitical uncertainties, potentially more US Federal Reserve rate hikes in the pipeline and inflation risks, domestic catalysts were a breakthrough for the S-REITs sector.

These include the fact that Singapore will transit to a “new normal reopening stance” under the Vaccinated Travel Framework (VTF) that commenced on April 1.

Major domestic relaxation protocols, such as a 75% return to office and a doubling of dine-in cap to 10 people per group have also propelled major moves within the reopening trade sectors of office, retail and hospitality, the analysts point out.

This coincided with the top-performing sectors for the month, namely hospitality, office and healthcare REITs, which saw gains of 14.4%, 5.8% and 5.1% m-o-m respectively.

The growth momentum remains intact as reopening trades see “a breath of fresh air” and the analysts expect an 8% CAGR in distribution per unit (DPU) growth for the sector in FY2022-2023.

Describing the market sentiment as “strong” in March, Wong and Tan says they think that in 2Q2022, share prices of S-REITs may trade sideways.

This is as market attention will likely rotate towards near term results and absorb the impact of inflation (such as utilities and maintenance costs) on distributions.

“In addition, the possibility of an even sharper interest rate hike by the Fed of 50 basis points (bps), as opposed to the initial 25 bps expected by the market, is an event that we are watching keenly,” they say.

Furthermore, they write that while safe-haven asset classes such as the S-REITs may be a temporary shelter for investors, the reversal of geopolitical tensions may also see investments flow out of the sector.

Wong and Tan expect positive news on both the border opening and relaxed measures, which should start to show in metrics come 1H2022. However, there is some lag time in the interim, mostly in 2Q2022, say the analysts.

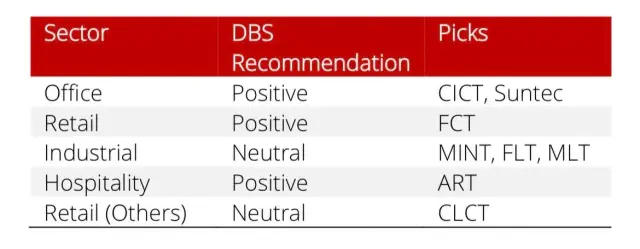
They have given a positive rating to the office, retail and hospitality sectors, with their top picks being Capitaland Integrated Commercial Trust (CICT), Suntec REIT, Fraser’s Centerpoint Trust (FCT) and Ascott Residence Trust (ART).

1.webp
 

TehSi99

Master Member
Joined
Oct 5, 2018
Messages
4,892
Reaction score
1,318
More talks about hospitality Reits now after opening.

Hope still a good time to enter.
 

Raynon

Senior Member
Joined
Jul 30, 2011
Messages
715
Reaction score
16
Can i check if my dividend for KORE is still sibject to withholding tax even though i hav suubmitted W-9 form?
 

Andrew833

Arch-Supremacy Member
Joined
Apr 7, 2017
Messages
17,571
Reaction score
6,145
Can i check if my dividend for KORE is still sibject to withholding tax even though i hav suubmitted W-9 form?
If you fill up the form for this withholding tax thing and submit, there will be no more withholding tax.
 

dappermen

Banned
Joined
Mar 5, 2017
Messages
8,663
Reaction score
1,017

i have none, cos Ultra big names which may not be "big" in price performance​

and many will assume : Things are looking up for office REITs? are Post-covid times really back to pre-cov times?

https://sg.finance.yahoo.com/news/better-buy-capitaland-integrated-commercial-100000400.html​


Portfolio composition​

032cbb97235285605635a4f7bbc0fc5e

First, we looked at the portfolio composition for both REITs.

CICT has nearly five times the number of properties that MCT has, and the valuation of these properties is also almost triple that of the latter.

In terms of country exposure, CICT has properties in three countries — Singapore, Germany, and Australia, while MCT only has properties in Singapore.(before propossed merged w MNACT)

Winner: CICT


Financials​

06d6af2ab75121de5bcb4e6b079d8dfc


Debt indicators


06bf1a17c576e71670ff2dea2bb8daa4

Things get interesting when we look at the next section on debt indicators.

Both REITs have nearly the same cost of debt at around 2.3% to 2.4%, but MCT has a slightly higher interest coverage ratio of 4.8 times.

MCT’s gearing level is also lower at 34.1%.

Do note, however, that MPACT’s gearing will stand at 39.2% if the merger goes through successfully.

For CICT, its recent acquisition of a Grade A office building at 79 Robinson Road will raise its aggregate leverage to around 41%.

Winner: MCT


Operating metrics​

679a473a669d031392d92dcf1d062f7b

The fourth area we looked at was operating metrics, namely portfolio occupancy and weighted average lease expiry (WALE).

MCT had a higher committed occupancy of 96.3% as of 31 December 2021, compared with CICT’s occupancy level of 93.9%.

If we drill down further into the retail and commercial components, MCT also does a little better.

Its retail portfolio (i.e. VivoCity) enjoyed 98.9% committed occupancy while CICT’s retail division saw occupancy of 96.8%.

CICT’s office occupancy stood at 91.5% while three of MCT’s office assets enjoyed more than 95% committed occupancy. Only one asset (mTower) had an occupancy level of 87.6%.

However, MCT had a slightly lower WALE compared with CICT due to the larger contribution of its retail component.

Winner: MCT


Dividend yield​

7d30e825257eee65fe4f053d0b43c79c

Finally, we get to the section that income investors can appreciate – the distribution per unit (DPU) cum dividend yield. - some of your fav items!

Really MCT (aft merge) the real winner if compared w CICT?​


demoforce1

Master Member
Joined
Apr 1, 2018
Messages
4,000
Reaction score
217

i have none, cos Ultra big names which may not be "big" in price performance​

and many will assume : Things are looking up for office REITs? are Post-covid times really back to pre-cov times?

https://sg.finance.yahoo.com/news/better-buy-capitaland-integrated-commercial-100000400.html​


Portfolio composition​

032cbb97235285605635a4f7bbc0fc5e

First, we looked at the portfolio composition for both REITs.

CICT has nearly five times the number of properties that MCT has, and the valuation of these properties is also almost triple that of the latter.

In terms of country exposure, CICT has properties in three countries — Singapore, Germany, and Australia, while MCT only has properties in Singapore.(before propossed merged w MNACT)

Winner: CICT


Financials​

06d6af2ab75121de5bcb4e6b079d8dfc


Debt indicators

06bf1a17c576e71670ff2dea2bb8daa4

Things get interesting when we look at the next section on debt indicators.

Both REITs have nearly the same cost of debt at around 2.3% to 2.4%, but MCT has a slightly higher interest coverage ratio of 4.8 times.

MCT’s gearing level is also lower at 34.1%.

Do note, however, that MPACT’s gearing will stand at 39.2% if the merger goes through successfully.

For CICT, its recent acquisition of a Grade A office building at 79 Robinson Road will raise its aggregate leverage to around 41%.

Winner: MCT


Operating metrics​

679a473a669d031392d92dcf1d062f7b

The fourth area we looked at was operating metrics, namely portfolio occupancy and weighted average lease expiry (WALE).

MCT had a higher committed occupancy of 96.3% as of 31 December 2021, compared with CICT’s occupancy level of 93.9%.

If we drill down further into the retail and commercial components, MCT also does a little better.

Its retail portfolio (i.e. VivoCity) enjoyed 98.9% committed occupancy while CICT’s retail division saw occupancy of 96.8%.

CICT’s office occupancy stood at 91.5% while three of MCT’s office assets enjoyed more than 95% committed occupancy. Only one asset (mTower) had an occupancy level of 87.6%.

However, MCT had a slightly lower WALE compared with CICT due to the larger contribution of its retail component.

Winner: MCT


Dividend yield​

7d30e825257eee65fe4f053d0b43c79c

Finally, we get to the section that income investors can appreciate – the distribution per unit (DPU) cum dividend yield. - some of your fav items!

Really MCT (aft merge) the real winner if compared w CICT?​

thanks for sharing, how about compare to Starhill?
 
Important Forum Advisory Note
This forum is moderated by volunteer moderators who will react only to members' feedback on posts. Moderators are not employees or representatives of HWZ Forums. Forum members and moderators are responsible for their own posts. Please refer to our Community Guidelines and Standards and Terms and Conditions for more information.
Top