

You are using an out of date browser. It may not display this or other websites correctly.
You should upgrade or use an alternative browser.
You should upgrade or use an alternative browser.
UOB ONE Account
- Thread starter pcmdan
- Start date
More options
Who Replied?

highsulphur
Greater Supremacy Member
- Joined
- Aug 16, 2011
- Messages
- 77,944
- Reaction score
- 40,443
Those days of 400+were shiokstart of 1.9%...BI is in...

Cumzilla
Master Member
- Joined
- Oct 28, 2002
- Messages
- 3,362
- Reaction score
- 216
$500++ BIThose days of 400+were shiok
need a clarification please...
If i can meet $600 eligible spend on UOB One credit card + Salary credit of required amount + 3 GIRO bill payments, for a S$100K deposit inside UOB One account, would the effective interest rate be 1.9% pa?
TIA
If i can meet $600 eligible spend on UOB One credit card + Salary credit of required amount + 3 GIRO bill payments, for a S$100K deposit inside UOB One account, would the effective interest rate be 1.9% pa?
TIA
You need the following 3 if you have salary crediting :need a clarification please...
If i can meet $600 eligible spend on UOB One credit card + Salary credit of required amount + 3 GIRO bill payments, for a S$100K deposit inside UOB One account, would the effective interest rate be 1.9% pa?
TIA
1. $150k Average Daily Balance for calendar month
2. $500 spend on eligible credit card and spend on eligible transactions for calendar month
3. Salary credit of at least $1600. 3x GIRO is not necessary if you have salary crediting
This gives ~1.9% pa based on $150k.
If you do not have salary crediting then the following applies :
1. $125k Average Daily Balance for calendar month
2. $500 spend on eligible credit card and spend on eligible transactions for calendar month
3. 3x GIRO is a must!
This gives ~1.4% pa based on $125k.
https://www.uob.com.sg/personal/save/everyday-accounts/one-account.page
No, 100k deposit effective is ~1.38%need a clarification please...
If i can meet $600 eligible spend on UOB One credit card + Salary credit of required amount + 3 GIRO bill payments, for a S$100K deposit inside UOB One account, would the effective interest rate be 1.9% pa?
TIA
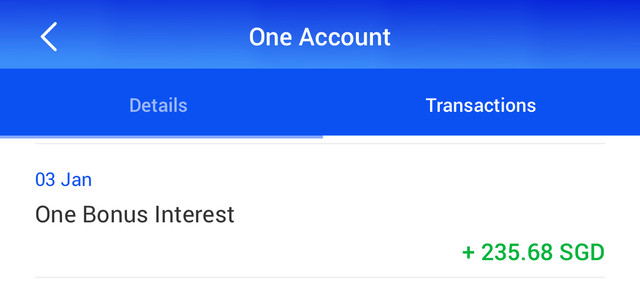
If reduce to 100k, what is the expected bonus interest ??Repeating post to share here :
Computed bonus interest for the first $150k principal amount (average daily balance),
and meet $500 card spend & $1.6k salary :
From 1st Dec 2025 onwards
28 days in the month = $212.87 (not yet verify)
29 days in the month = $220.47 (not yet verify)
30 days in the month = $228.08 (not yet verify)
31 days in the month = $235.68 (not yet verify)
Disclaimer : actual amounts may differ by a few cents due to rounding off, pls refer to bank for eventual amounts .....
Old bonus interest. pls see
https://forums.hardwarezone.com.sg/threads/uob-one-account.5037662/post-157941641
Think of reducing as not as good as before...what is the other saving acct option besides ocbc and hsbc ??
Thks
Just use the website you check ....If reduce to 100k, what is the expected bonus interest ??
Think of reducing as not as good as before...what is the other saving acct option besides ocbc and hsbc ??
Thks
https://www.uob.com.sg/personal/save/everyday-accounts/one-account.page
Do note if you are still on the Income tax + PayNow promo, you need to maintain $150k to reap max benefit ....
https://forums.hardwarezone.com.sg/threads/uob-one-account.5037662/page-556#post-158188536
Thanks for another data point contribution ....
highsulphur
Greater Supremacy Member
- Joined
- Aug 16, 2011
- Messages
- 77,944
- Reaction score
- 40,443
But you don't have to invest with UOBEven if you include the $50 income tax rebate, UOB One account's interest rate is still not competitive compared to DBS Multiplier, SCB BonusSaver and OCBC 360..
iduncheckmail
Supremacy Member
- Joined
- Nov 24, 2002
- Messages
- 6,830
- Reaction score
- 3,437
dont worry , eventually all also will congregate down to a narrow band.Even if you include the $50 income tax rebate, UOB One account's interest rate is still not competitive compared to DBS Multiplier, SCB BonusSaver and OCBC 360..

iadpotato
Senior Member
- Joined
- Aug 5, 2009
- Messages
- 1,520
- Reaction score
- 249
Personally, BonusSaver doesn’t feel worth it since the $1000 spend on their card doesn’t have any rebates. And the wealth and insure cats are too difficult for the average Joe to achieve.Even if you include the $50 income tax rebate, UOB One account's interest rate is still not competitive compared to DBS Multiplier, SCB BonusSaver and OCBC 360..
As for OCBC, the monthly increment of $500 is kinda stupid I feel. And their cards are not exactly fantastic.

JetStorm
Senior Member
- Joined
- May 27, 2007
- Messages
- 1,860
- Reaction score
- 319
No one solution fits all.
For example, If you work for certain banks, your salary account has to be by that bank one, blocking you from taking advantage of getting higher interest from salary credits. Not every bank lets you do the PAYNOW SALA method also.
So we just work within our constrains. If you have no such limitation, good for you. But end of the day we all such want simplicity and less admin work. Its a hassle to keep switching banks for our salary and spending account.
If work in bank likely pay well mah, no need haggle for few % interest. Bank give bonus and annual increment surely more than compensate for such constraints.No one solution fits all.
For example, If you work for certain banks, your salary account has to be by that bank one, blocking you from taking advantage of getting higher interest from salary credits. Not every bank lets you do the PAYNOW SALA method also.
So we just work within our constrains. If you have no such limitation, good for you. But end of the day we all such want simplicity and less admin work. Its a hassle to keep switching banks for our salary and spending account.
DevilPlate
Arch-Supremacy Member
- Joined
- Nov 22, 2020
- Messages
- 12,236
- Reaction score
- 5,155
Alot of dragons here max out liao including their spouses acct leh?Even if you include the $50 income tax rebate, UOB One account's interest rate is still not competitive compared to DBS Multiplier, SCB BonusSaver and OCBC 360..
so bopian UOB 1 or even UOB stash also have.

JetStorm
Senior Member
- Joined
- May 27, 2007
- Messages
- 1,860
- Reaction score
- 319
Can squeeze out some money from interest just squeeze. Why let the banks earn?If work in bank likely pay well mah, no need haggle for few % interest. Bank give bonus and annual increment surely more than compensate for such constraints.
Bank use your money earn more interest than you. You earn 4% right now is considered quite high, but bank will earn more than 10% by using your money.Alot of dragons here max out liao including their spouses acct leh?
so bopian UOB 1 or even UOB stash also have.
Important Forum Advisory Note
This forum is moderated by volunteer moderators who will react only to members' feedback on posts. Moderators are not employees or representatives of HWZ Forums. Forum members and moderators are responsible for their own posts.
Please refer to our Community Guidelines and Standards and Terms and Conditions for more information.

