
U dunno how to read?
Clearly stated INCOME and transactions
Clearly stated INCOME and transactions
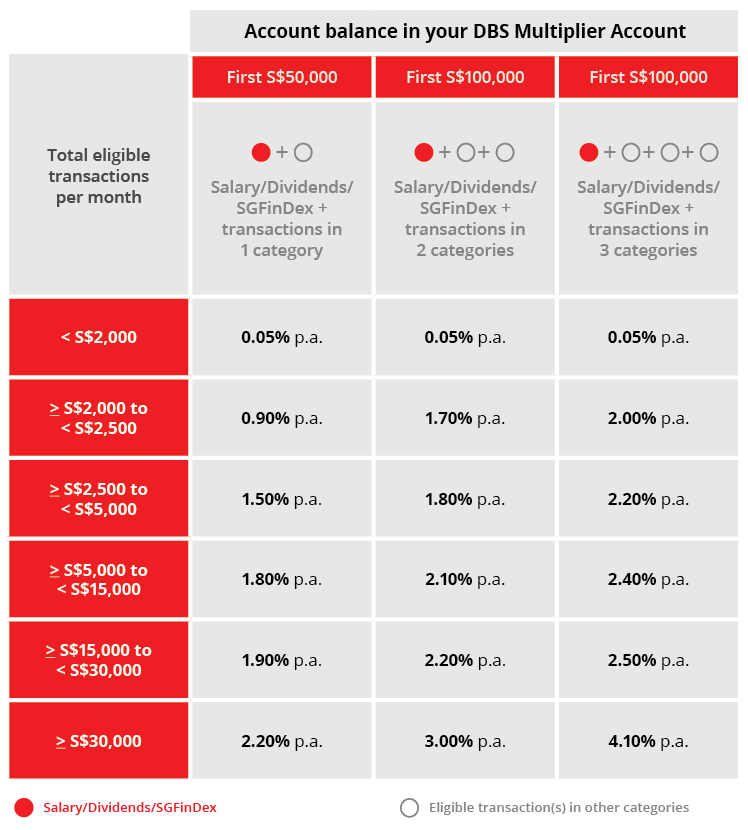
"Total eligible transactions per month"
"Total eligible transactions per month"

You chose to do selective reading?U dunno how to read?
Clearly stated INCOME and transactions
You chose to do selective reading?
hmmmm got anything to do with DBS? sounds irrelevant.lol
Now i know why man u lost
doubt you will also. so no diff.U won't understand
Have a great day
doubt you will also. so no diff.
I do. i am just saying they call it "transactions". every cent from your salary, every cent from your loan repayment, every cent from purchase of insurance, every cent from investment count towards this 30k in "transactions".U know if your income is $20k and loan repayment $10k u already hit max tier
Card spend, investment and insurance can be just 1 cent
yes, but it doesn't change the fact that "Total eligible transactions per month" is the header of the different bands.Your picture also got red and white circles which shows clearly income vs txns, as denoted below
yes, but it doesn't change the fact that "Total eligible transactions per month" is the header of the different bands.
Well DBS is using "transaction" loosely. but if you think about it. receiving salary is a form of a "transaction". you offer your time to work and your employer pays you. so as much as it is a technicality, i don't see anything wrong with it especially when that's how DBS is using it alsoIt's just a technicality. Clearly income and loan are not typical transactions that we normally associate with spendings. In fact real spendings can be even be $0
Well DBS is using "transaction" loosely. but if you think about it. receiving salary is a form of a "transaction". you offer your time to work and your employer pays you. so as much as it is a technicality, i don't see anything wrong with it especially when that's how DBS is using it also
Dividend is a passive income
And Loan is a different thing
is paylah count on top of cc spend?
Digital banks have some major advantages over the retail banks in term of expenditure, and some of the savings will be passed on to consumers.
- No need for physical stores and ATMS (no rental, maintainence, staff, etc).
- If everything is online, some of low value work can be done though oversea contract staffs which is cheaper.
- Emphasis of mobile payment and online banking, integrate insurance and others (Grab is planning to do that). Technically also bypass insurance agents fees, master & VISA, etc.
If you compare the interest rate of retail vs online banks in USA, it is can be at least 1% more in difference.
There is some increasing free rider issue for the retail banks. I could ride on ATM of retail banks by putting a minimum amount but I park the bulk of $$ in online banks. This is already happening with CIMB saver, BOC, etc. These banks do not have enough ATM for decent usage and ppl will ride on local banks ATM.
Digital banks are not magicians. Interests don’t come from the air.
What products are digital banks going to push to pay for interests?
It is very easy to collect deposits as long as you pay higher interests. But how does a bank earn income to pay interests on deposit is the question.
Currently there is no liquid safe instrument paying 2%.
How SingLife and the alike achieve higher interest is through term mismatch.
On the topic of digital bank, HK provides a glimpse for SG market:
https://asia.nikkei.com/Business/Bu...ups-lead-region-s-charge-into-virtual-banking
it is so called regulatory arbitrage.
I really would like to see any of the digital banks reach the size of the "big" 3 and see how they can offer anything, but market interest rate.
it is so called regulatory arbitrage.
I really would like to see any of the digital banks reach the size of the "big" 3 and see how they can offer anything, but market interest rate.
