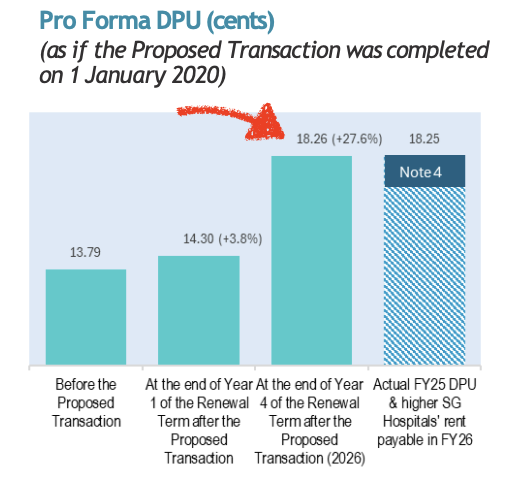
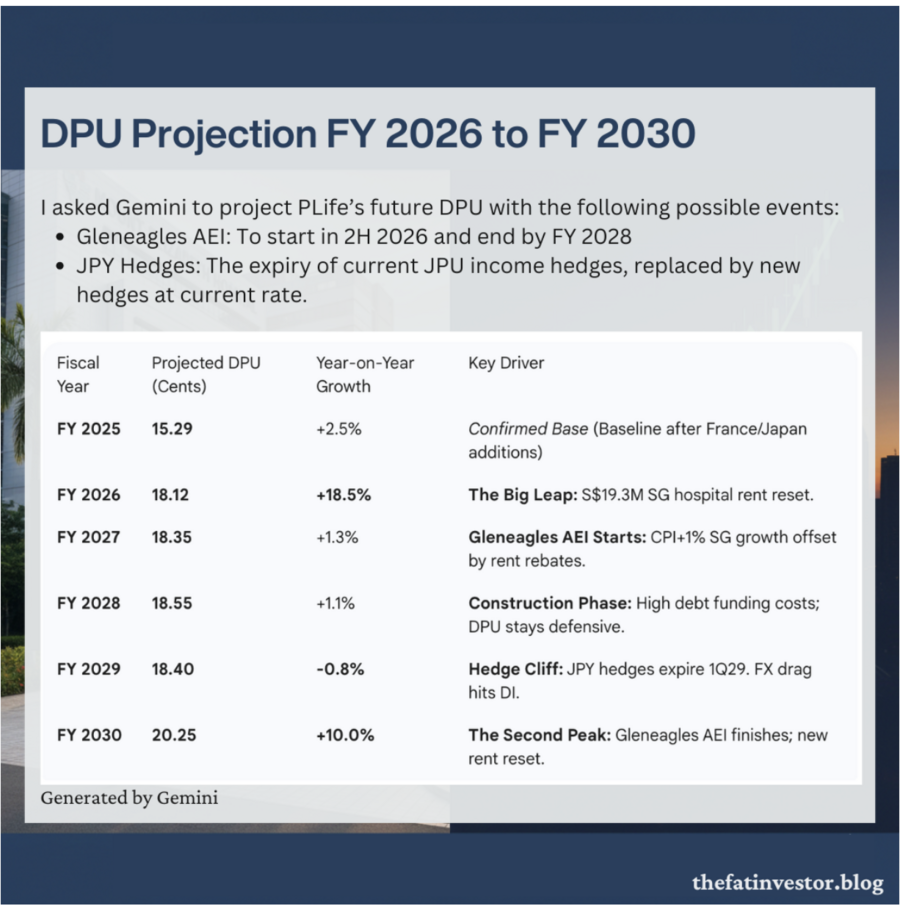
0.5 risk free vs 3.6% risk, definitely your logic is very sound. Hospital reit very safe i also fully agree. But this is only one dimensional. But pay 60% premium for safety is exorbitant, and they are not even temasek or gic backed. Are there betterer deals? Ascendas and CICT even safer, solid backing and their premium is only 24% and 15%, yet their yield is better. Dbs also way way overpriced, but you see their dividend won't lose to people. So if u compare all these, then your 3.6% where got attractive? I suspect it could be because parkway is the only one in singapore, so buyers who want healthcare all buy this one causing the price (denominator) to overshoot, and then causing they yield% to suffer. If they have some competitors then probably the valuation and yield might not be so bad.